

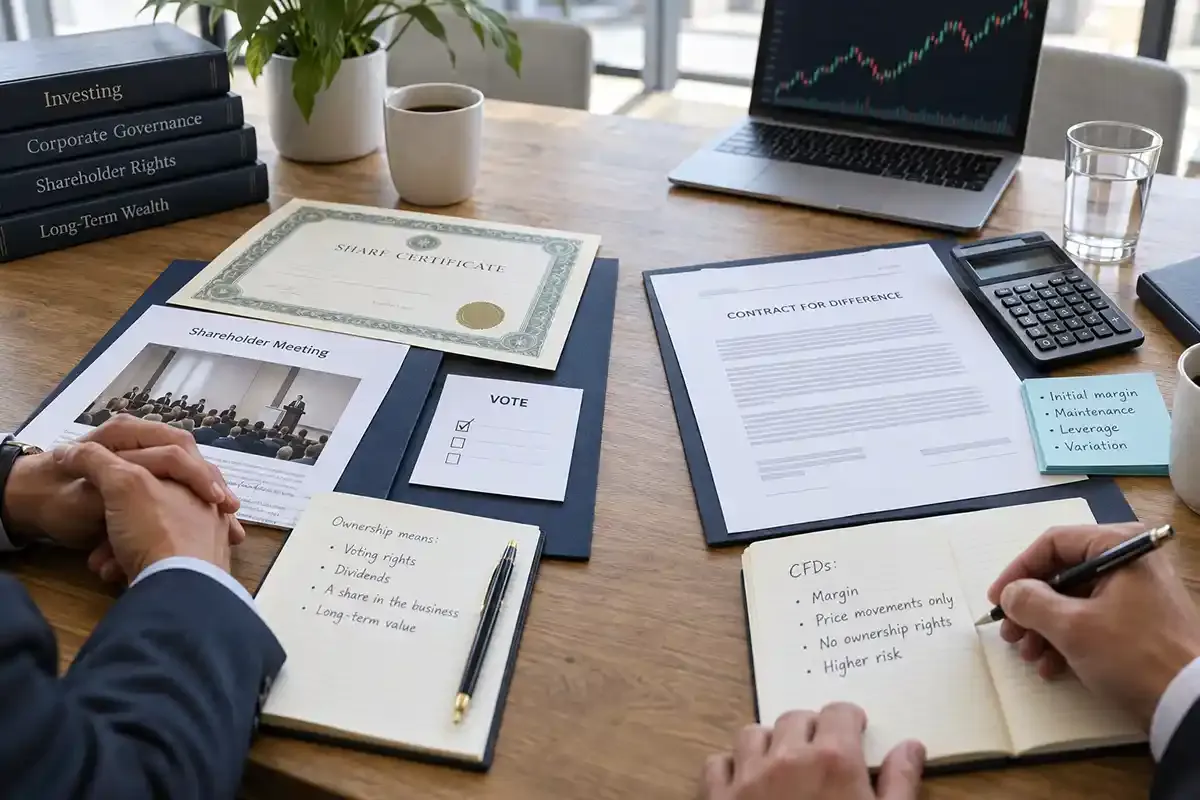

A share and a CFD can reference the same company price, but they create different legal and operational relationships. A shareholder owns an equity interest. A CFD client owns a contract whose value follows agreed price changes.
The core legal difference
Investor.gov describes stock as an ownership interest in a company. Common shareholders may vote and may receive dividends when declared. A CFD is a derivative: its value is based on an underlying asset, while the client's rights come from the contract and provider terms.
This distinction matters even when two screens show similar price charts. The instruments can differ in rights, leverage, custody, tax treatment, holding costs and what happens if an intermediary fails.
Rights that follow share ownership
Depending on the share class and jurisdiction, an owner may vote for directors, receive meeting materials, participate in certain corporate actions and receive a declared dividend. These rights attach to the security and the way it is registered or held through a broker or custodian.
A CFD client is not placed on the share register. There is no direct vote or shareholder meeting entitlement. A contractual adjustment can mirror some economic effect, such as a dividend, without transferring the legal right.
Custody and counterparty structure
Direct ownership normally depends on a broker, nominee, central securities depository or custodian. The investor should understand who is the registered holder and how assets are separated.
A CFD is an over-the-counter relationship with the provider. The client depends on that entity's solvency, controls, pricing, execution and applicable protections. The FMA advises derivative users to assess both market risk and counterparty creditworthiness.
Leverage, short exposure and loss
Direct shares are often purchased for their full cash value, although lending or margin facilities can add leverage separately. A CFD is commonly margin-based, so a smaller cash amount supports a larger notional exposure. This increases sensitivity to price movement and can trigger close-out requirements.
A CFD may also provide short exposure without the client arranging a stock borrow directly. Availability can change with market conditions and product rules. Short losses can grow as the price rises, and financing or borrow-related adjustments may apply.
Costs and holding period
Share ownership may involve brokerage, custody, exchange, conversion and tax costs. A CFD may involve spread, commission, overnight financing, conversion and adjustment charges. Financing can become material over a long holding period, so a lower entry cost does not establish a lower total cost.
Compare costs over the intended period and under more than one price scenario. Spreads, Commissions and Total Trading Cost provides a reusable framework.
Dividends and corporate actions
A declared dividend belongs to eligible shareholders under the market's record and ex-dividend rules. A CFD provider may debit or credit an adjustment to reflect part of the economic effect. Splits, rights issues, mergers and delistings can also lead to contractual position changes.
The result must be checked against the product terms rather than inferred from shareholder treatment. Direct ownership and a derivative adjustment can differ in timing, tax, rounding and eligibility.
A comparison checklist
- Name the legal instrument and contracting entity.
- Decide whether ownership rights or only price exposure are required.
- Compare full cash value with notional exposure and margin.
- List all transaction and holding costs.
- Check voting, dividends and corporate-action treatment.
- Assess custody or counterparty dependencies.
- Confirm trading hours, liquidity and exit conditions.
Neither structure is automatically appropriate for every purpose. Start with the objective, then compare the actual product documents and risks.