

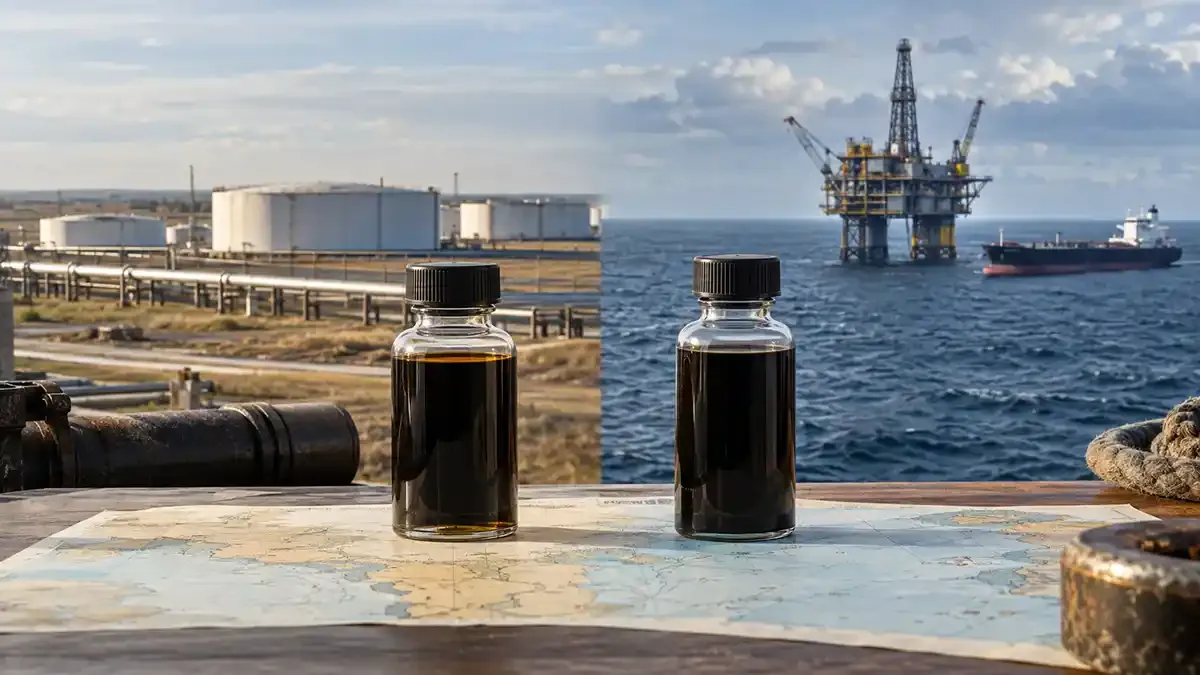

WTI and Brent are the two crude-oil names most often used in market headlines. They usually share broad global drivers, but each is anchored to a different physical and commercial system. Their price difference can therefore contain information about location, transport and regional balance.
What makes a crude-oil benchmark
A useful benchmark has active price discovery and a sufficiently clear relationship to physical supply. Other crude grades can be priced at premiums or discounts that reflect quality, transport and regional conditions. A benchmark is influential because market participants can use it consistently, not because every barrel is identical to it.
WTI: the US inland reference
West Texas Intermediate is a light, sweet crude associated with the US market and the Cushing, Oklahoma delivery hub for the NYMEX light sweet crude futures contract. Cushing connects pipelines and storage in the mid-continent system.
US production, Cushing inventories, pipeline flows, refinery demand and export capacity can all affect WTI’s regional context. When barrels have difficulty moving away from an inland hub, local supply pressure can change WTI relative to seaborne alternatives.
Brent: the seaborne reference
Brent represents a North Sea-linked crude complex and serves as a widely used reference for seaborne oil. Access to ships and international trade helps connect it to conditions across Europe, Africa, the Middle East and Asia.
North Sea supply, maintenance, shipping costs, geopolitical risk and broad import demand can influence the Brent context. The benchmark system has evolved over time, so current ICE documentation is the source for contract methodology and deliverable grades.
Quality matters, but location often dominates
Both benchmarks are commonly classified as light and sweet, terms that refer broadly to density and sulphur content. Refineries value crude grades differently because equipment and desired product yields differ. Yet even similar-quality oil can trade at different prices when transport and storage conditions differ.
For a beginner, the practical rule is to check quality, location and delivery together. None provides a complete explanation alone.
What moves the Brent–WTI spread
- Relative US and international crude production.
- Cushing and coastal inventory conditions.
- Pipeline capacity between production, storage, refineries and export terminals.
- US export economics and tanker freight.
- North Sea supply, maintenance and benchmark availability.
- Regional refinery demand, outages and crude-quality preferences.
- Geopolitical events, sanctions and global demand expectations.
The spread is not fixed. Brent can trade above or below WTI, and a change can come from either side. Analyse the two outright prices and their physical context before assigning a cause.
Spot, futures and CFD prices are not identical
A spot assessment, a specific futures month and a CFD can display different values. Futures prices reflect contract month and delivery terms; CFDs follow the provider’s pricing and rollover rules. Contract expiry, the forward curve, financing and market hours can all matter.
Begin with Energy CFD foundations, then confirm whether the RG symbol refers to WTI or Brent, the contract size, quoted currency, hours and rollover or financing treatment.
A practical comparison checklist
- Label each series clearly as spot, futures month or CFD.
- Confirm the benchmark location and delivery convention.
- Use the same timestamp and currency for comparison.
- Check whether one market was closed or less liquid.
- Review inventories, transport constraints and regional refinery demand.
- Do not treat a widening or narrowing spread as a standalone trading signal.
WTI and Brent are connected views of the oil system. Their difference is most useful when it is tied back to the physical routes that make each benchmark distinct.