

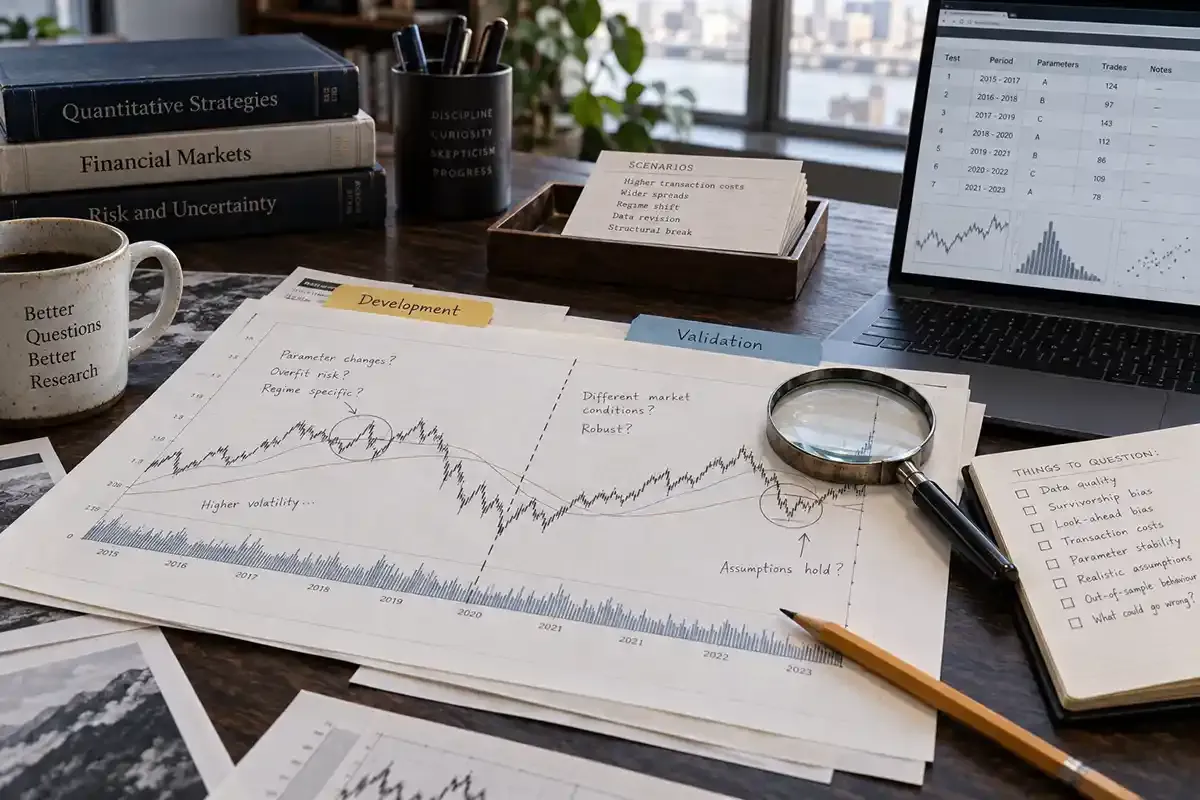

The MetaTrader Strategy Tester can run an Expert Advisor over historical data, inspect individual operations and compare parameter sets. It is valuable for finding coding errors and understanding rule behaviour. Its output remains hypothetical: the market, account and operational environment in live use will not exactly repeat the test.
What a backtest does
A test combines program code, input parameters, symbol settings, a selected period and a modelling method. MT5 can test multi-currency strategies and use multiple processing agents; MT4 provides its own tester and modelling choices. More computational power increases the number of experiments—it does not make weak assumptions true.
Data and modelling risk
History and tick generation
Missing history, time-zone differences, bar construction and simulated ticks can change when rules trigger. MT5 offers modes ranging from real ticks supplied through the broker to simplified OHLC or open-price methods. Faster modes omit detail and should be treated as rough filters, not interchangeable results.
Symbol and account settings
Contract size, price precision, minimum volume, margin, swap, commission, spread and filling rules affect outcomes. A test that omits or misstates costs can materially overstate performance. Settings should match the intended product and be recorded with the result.
Overfitting and hindsight
Optimisation searches many parameter combinations. If the same period is repeatedly used to select and judge a strategy, the process can fit random features that will not persist. A smooth curve can therefore describe the search process better than the underlying rule.
NFA guidance on hypothetical results highlights hindsight, absent financial risk and market factors such as liquidity and slippage. Those limitations remain relevant even when the report looks detailed.
A better validation design
- Write the rule and success criteria before seeing the final period.
- Reserve data that is not used for parameter selection.
- Use realistic spread, commission, financing and execution assumptions.
- Test small changes to parameters and start dates.
- Inspect trades, drawdowns and concentration—not only total return.
- Include adverse periods and missing-data checks.
- Run forward or demo observation after historical testing.
- Document every material change and repeat the approval process.
MT5 forward testing can divide the selected period into optimisation and later validation sections. This helps expose some fitting, but both parts remain historical and selected by the researcher.
What live trading adds
Live use introduces changing spreads, queue position, slippage, rejected requests, partial execution, connection loss, platform updates and human intervention. The strategy can also alter the market exposure of the account through overlapping positions or margin use.
Expert Advisors, MQL4 and MQL5 covers deployment controls, while Platform Connectivity and Operational Trading Risk covers failures outside the signal logic.
Reading a test report
Review trade count, time in market, maximum drawdown, average outcome, concentration by symbol and period, and sensitivity to assumptions. A small number of trades or one exceptional interval can dominate the headline. Report both favourable and adverse findings, and label all simulated results clearly.
Backtesting is most useful as falsification: it can reveal that a rule fails under stated conditions. It cannot establish that future profits will occur.