

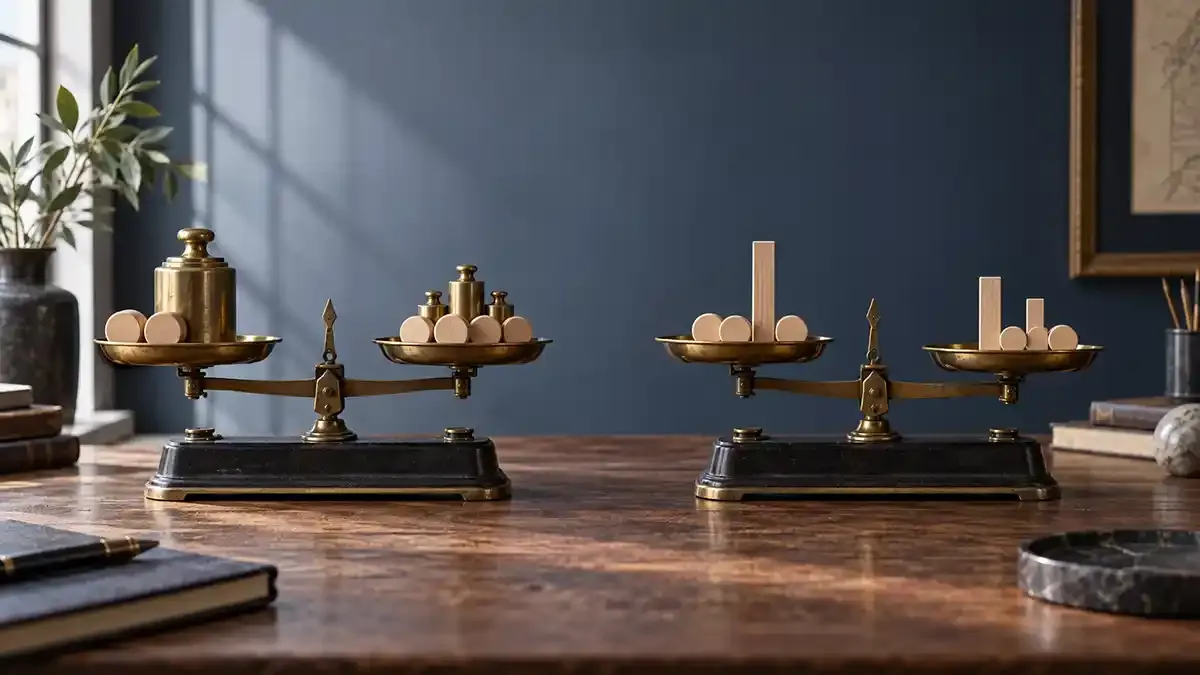

Two indices can hold many of the same companies and still produce different results. The reason is weighting: the rule that decides how much influence each constituent receives.
Market-cap weighting
Market capitalisation is share price multiplied by shares outstanding. Many equity indices use float-adjusted market capitalisation, reducing the share count for holdings considered unavailable to public investors. A constituent’s weight is then related to its eligible value as a share of the index total.
If a company’s eligible value grows relative to the rest of the basket, its weight and influence generally grow. This allows the index to reflect changes in the market’s valuation of constituent companies, but it can also produce concentration in a small group of very large firms.
Price weighting
A price-weighted index gives more influence to a constituent with a higher per-share price. Company A trading at a higher share price can carry more weight than a much larger Company B whose shares trade at a lower price. Shares outstanding and total company value do not directly set the weight.
Because share price is the operative input, stock splits require divisor adjustment. A split reduces the quoted price without changing the shareholder’s proportional ownership or, by itself, the company’s total value. Without an adjustment, the index would move mechanically.
A simple comparison
Imagine three companies. One is economically very large but has a moderate share price. Another is smaller but has a high share price. The third is small on both measures. In a market-cap index, the first company is likely to dominate. In a price-weighted index, the second may have the greatest influence.
This is why the same earnings surprise can have a different index effect across benchmarks. Percentage price movement must be considered alongside the weight created by the methodology.
Modified, capped and equal-weight variations
Providers can modify market-cap weighting with single-company or group caps. Some indices apply rules at scheduled rebalances to reduce excessive concentration. Equal-weight indices give each constituent the same target weight at the rebalance date, after which market movement causes weights to drift.
“Modified market cap” is not one universal formula. Each methodology defines its own thresholds, caps and redistribution steps. Read the source document rather than inferring the rules from the label.
What weighting means for index risk
A benchmark with many constituents can still depend heavily on a few leaders. Concentration increases sensitivity to their earnings, valuations, sectors and idiosyncratic events. Price weighting can create influence based on nominal share price, while market-cap weighting can amplify the effect of the largest firms.
Use market breadth and concentration to look beneath the headline. Advancers versus decliners, sector contribution and equal-weight comparisons can help show whether participation is broad, but none is a standalone forecast.
Index maintenance and the divisor
Both methods rely on maintenance rules. Corporate actions, constituent changes and rebalances may change shares, prices or weights without representing an economic market move. Divisor adjustments or equivalent mechanisms preserve continuity according to the methodology.
The construction sequence is covered in how stock indices are built. For CFD exposure, remember that the product adds its own point value, spread, margin, financing, hours and execution terms.
A practical reading checklist
- Identify the exact weighting method and calculation series.
- Review the largest constituent and sector weights.
- Check caps, buffers and rebalance timing.
- Understand split and corporate-action treatment.
- Compare percentage moves, not raw index points alone.
- For a derivative, add the separate product specification and risk layer from Index CFD foundations.